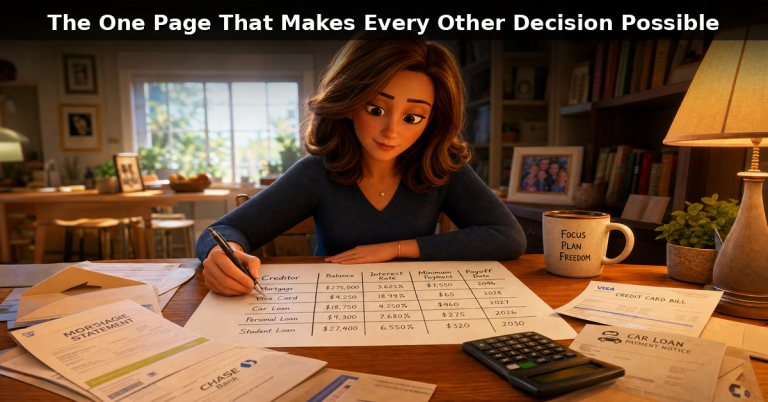
The One Page That Makes Every Other Decision Possible
Most people know roughly what they owe. They know the mortgage is massive, that one particular credit card is a bit embarrassing, and that the car payment gets pulled from their account on the 15th of the month. But knowing roughly is entirely different from knowing clearly. Rough knowledge keeps your debt feeling vague and somewhat shameful. Clear knowledge, on the other hand, turns it into a simple list of numbers, and numbers are something you can actually work with.
This exercise is all about building that list. One single page. Every single debt. All the data fields that actually matter. It takes about an hour of your time, but it may well be the most useful financial hour you spend all year.
Why One Page Changes Everything
When your debts live in separate places, a mortgage statement over here, a credit card app over there, and a student loan login you have not touched since last spring, your brain simply cannot hold the full picture at once. As a result, you make decisions in isolation. You might pay a little extra on the car this month, let the credit card ride, and completely forget that the home equity line even has a variable rate.
A single table forces you to confront a complete view. You immediately see which balance is the largest, which interest rate is the highest, which payoff date stretches the furthest into the future, and which account has a promotional window quietly ticking down. That complete, unified view is exactly what makes it possible to prioritize your actions intelligently rather than purely instinctively.
The initial sting is very real. Seeing every debt listed in one row, all totaled up at the bottom, can feel incredibly heavy. That feeling is worth sitting with for a moment, and then you must move past it. The number itself did not change just because you wrote it down. It was already true. The difference is that now you can actually do something about it.
The Fields That Belong in Every Row
Build your table using one row per debt. These are the specific columns worth including:
Creditor: Who you owe the money to. This seems straightforward, but you need to write it down. Seeing eight distinct rows is very different from having a vague sense of “several accounts.”
Current Balance: Pull the most recent statement or log in today to get the exact figure. Estimates simply will not do here.
Interest Rate (APR): This is the annual percentage rate, not the monthly rate. For variable-rate accounts, note the current rate and explicitly write “variable” so it does not get mistaken for a fixed rate later.
Fixed or Variable: A fixed rate stays exactly where it is. A variable rate can rise. This distinction matters enormously for any long-range financial planning.
Minimum Payment: This is the floor, not the target. Knowing the minimum on every single account tells you your baseline monthly obligation, which is the number below which things start to break.
Actual Monthly Payment: This is what you are actually paying right now. It is often higher than the minimum, and that difference matters significantly.
Remaining Term: How many months or years remain until this debt is gone at your current payment level. Your most recent statement often shows this clearly; if it does not, your servicer can tell you.
Current Payoff Date: The specific calendar month and year when this debt ends if absolutely nothing changes. This is the number that tends to produce the sharpest reaction. A 2039 mortgage is expected, but a 2031 credit card is a serious wake-up call.
What Secures It: Is this debt backed by your home, your car, something else entirely, or nothing at all? Secured debts carry very different stakes if payments are missed.
Prepayment Restrictions: Some loans, particularly certain mortgages and personal loans, carry prepayment penalties for paying ahead of schedule. Check your loan documents or call your servicer to find out. Most people discover there are no penalties, but it is always worth confirming before you start sending extra payments.
Promotional Rate Expiry: If any balance carries a 0% or reduced introductory rate, write down the exact date it expires and the rate it converts to afterward. This is often the most time-sensitive number in the entire table.
A Few Notes on Gathering the Data
You do not need to do this from memory. Log into each account, pull the most recent statement, and copy the numbers directly. For the mortgage specifically, your annual escrow and amortization statement will have the current balance and the remaining term clearly listed.
If you are not sure whether a loan has prepayment restrictions, the answer lives in your original loan documents, usually in a section labeled “Prepayment,” or a quick call to customer service can confirm it for you. Most representatives can also tell you the exact payoff amount as of any given date.
For variable-rate accounts, make sure to note both the current rate and what it is indexed to, such as the prime rate. You will not be able to predict exactly where it goes, but you will know to check it periodically.
What the Table Tells You That Nothing Else Does
Once the table is fully complete, a few things tend to become obvious that simply were not before.
The total. Add up every current balance. That single sum, which is possibly the first time you have ever calculated it, is the number your plan needs to reduce to zero.
The rate landscape. Sorted by APR, the table shows clearly where interest is doing the most damage. A 22% credit card in a sea of 6% to 7% debts stands out immediately.
The timeline spread. Sorted by payoff date, you can see exactly which debts resolve soonest on their own and which will outlast almost everything else in your financial life.
The promotional cliff. Any row with a promo expiry date has a hard deadline. Knowing it is sitting right there in the table, rather than buried in an email, makes it much harder to accidentally miss.
Tools like Debt|Done|Date. are built around exactly this kind of structured inventory, and they use it to project what happens to every payoff date when you redirect even small amounts of extra payment. But the table itself, even if it is just on a printed piece of paper, is where the real work begins.
Start With What You Have
You do not need a perfect spreadsheet on day one. A ruled notebook, a folded piece of paper, or even a notes app will work, as long as the format lets you see every row at once. Fill in what you can today and track down the remaining fields over the next few days.
The goal is not to create a beautiful document. The goal is one honest page that holds the complete picture of exactly where you stand. Every prioritization decision, every extra-payment question, and every “should we focus here or there?” conversation gets easier once that page exists.
Build it. Then you have something real to work with.
Get your “one page” started: HERE
Your Debt Resolved publishes this article for general education only. It is not financial, legal, tax, or investment advice, and it is not a recommendation of any specific product, lender, or strategy. Mortgage acceleration involves voluntary extra principal payments, and there is no guaranteed payoff date or savings amount. Your situation is unique; consult a licensed professional before acting. Individual results vary.