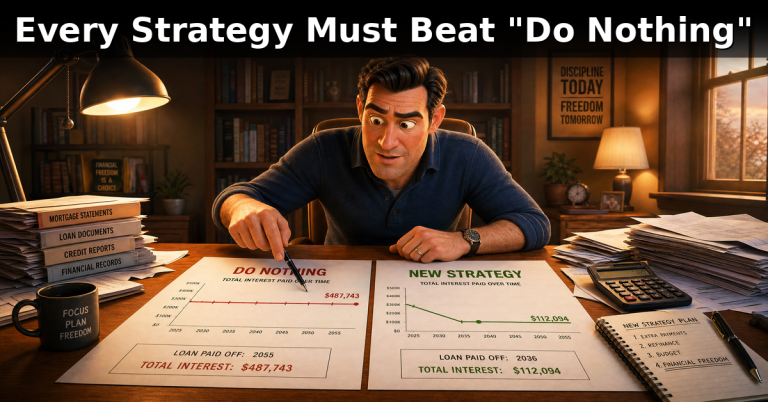
Every Strategy Must Beat "Do Nothing"
Most personal finance advice arrives wearing a costume. That costume might be a catchy name, a colorful chart, or a confident voice telling you this method is the one that finally works. Before any of that grabs your attention, there is one question worth asking first: compared to what?
Your “do nothing” baseline, which means your current loans and payments remaining unchanged forever, is the most honest yardstick you have. Any strategy that cannot beat it on both the payoff date and total interest paid has simply failed in public, no matter how well it was dressed.
What “Do Nothing” Actually Looks Like
“Do nothing” does not mean ignoring your debt. It means continuing exactly what you are already doing, which is making the minimum required payment on every balance, on time, every single month, until each loan reaches zero.
Most households have never actually looked closely at this number. They know roughly what they owe, but they have not sat down and calculated the exact month their last payment is due or the total dollars they will hand over to get there. That figure is often surprising, and that is precisely the point. Once you know it clearly, you have a real target to beat.
For example, a household carrying a mortgage and two other balances might find that doing nothing results in their last payment landing 22 years from now, with a total interest cost well into the six figures. That number is not there to scare anyone. It is there to serve as a benchmark.
The Two Numbers That Matter
Any strategy worth considering has to move at least one of these two levers, and ideally both:
Payoff date: the calendar month when the last balance reaches zero.
Total interest paid: every dollar paid to lenders above and beyond the principal.
These two numbers are related but not identical. A strategy might shorten your payoff timeline but, because of fees or other costs, leave the total interest relatively unchanged. A strategy might reduce interest on paper while stretching your timeline in a way that quietly costs you elsewhere. Running both numbers keeps those trade-offs completely visible.
This is why “do nothing” needs to be calculated, not estimated. Vague intuition about what you owe is not a benchmark. A specific month and a specific dollar figure provide the clarity you need.
Why This Habit Makes You Un-Sellable
The personal finance industry is massive, and some corners of it benefit when you feel like your current path is failing you. Products and programs are much easier to sell to someone who has never clearly defined what they are trying to beat.
When you know your baseline numbers, something very useful happens: you become harder to impress with vague claims. “Save thousands in interest” means absolutely nothing until you ask, “compared to my current path, how much exactly?” “Pay off debt faster” is an empty promise until you ask, “faster than when, specifically?”
This is not cynicism. Most tools and strategies that get promoted genuinely do help some households. The discipline of requiring a clear comparison simply filters out the ones that would help you less than doing nothing would, or worse, cost you more.
Think of it as a very low bar with very high value. The bar is simple: beat my current payoff date and my current total interest cost. If a strategy clears that bar by a meaningful margin, it deserves a closer look. If it does not clear it at all, it should be set aside calmly and without regret.
How to Run the Comparison
The math involved is not complicated, but it does require complete information. For each debt, you need:
Current balance
Interest rate
Minimum required payment
Any fixed payoff term (as with a mortgage)
With those inputs, you can calculate exactly where your do-nothing path ends. Your Debt Resolved is built specifically around this kind of calculation. It maps out the exact month each balance reaches zero under your current plan, so that any proposed change has a clear before-and-after to stand against.
Once you have your baseline, testing a strategy becomes straightforward. If you are considering paying an extra amount each month on one specific balance, calculate the new payoff date and new total interest across all your debts. If both numbers improve, the strategy passes. If they do not, it fails the test, and you have that answer before spending a single dollar.
A Practical Framing for Every Decision
When any debt-related idea comes across your path, whether it is a new payment method, a program, a restructuring suggestion, or anything else, you can run it through three quick questions:
What will my payoff date be if I do this?
What will my total interest paid be if I do this?
Are both of those numbers better than my current path?