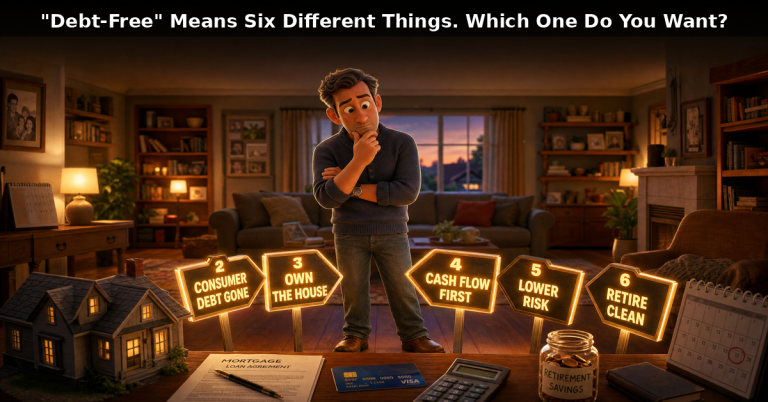
"Debt Free" Means Six Different Things.
Key Takeaways
This article identifies at least six distinct versions of “debt-free,” including total zero balance freedom, consumer-debt elimination, mortgage payoff, cash-flow relief, risk reduction, and retiring without payments, each pointing toward a different strategy.
Pursuing total debt freedom often means directing money toward low-interest debt like a mortgage that might otherwise fund retirement accounts, making it a values-driven trade-off rather than a purely mathematical one.
Refinancing can appear to be progress toward paying off a home while actually working against that goal, because extending the loan term resets the amortization clock and can increase lifetime interest even as the monthly payment drops.
For households prioritizing cash flow, paying off a smaller debt before a larger one can make sense even when interest-rate logic points the other way, because the freed-up monthly cash matters more than the mathematical optimum.
Debt that feels manageable on a working income can become genuinely difficult on a fixed income, making “retiring clean,” arriving at retirement with no debt obligations, one of the most urgent forms of the debt-free goal for many households.
Most people say they want to be “debt-free” the same way they say they want to be “healthy.” It feels obvious, and it feels good. But the moment you start making real decisions, the goal begins to splinter. Should you attack the mortgage or the credit cards? Make extra principal payments or invest the difference? Refinance or stay the course?
Those questions don’t have universal answers. They have answers that depend on which version of debt-free you’re actually chasing. There are at least six, and they point in surprisingly different directions.
1. Total Freedom: Zero Balances, No Exceptions
This is the purest form, no mortgage, no car loan, no student debt, no credit card balance. Nothing owed to anyone.
For some households, this is the only version that matters. There’s a real psychological weight to carrying any debt at all, and eliminating it entirely creates a sense of security that a spreadsheet simply can’t capture. That’s a completely legitimate goal.
The trade-off worth understanding is this: pursuing this version often means directing money toward low-interest debt, like a mortgage, that might otherwise fund retirement accounts or other priorities. Neither choice is wrong; they’re just different paths.
2. Consumer Debt Gone: The House Stays, Everything Else Goes
Many households draw a mental line between “bad debt” and “acceptable debt.” In this version, the goal is eliminating credit cards, personal loans, car payments, and possibly student loans, while continuing to make normal mortgage payments.
The logic is usually interest-rate driven. Consumer debt often carries double-digit rates. A mortgage is frequently much lower, and the interest may have tax implications worth exploring with a qualified tax professional. Getting rid of the high-rate obligations first can free up significant monthly cash, which then becomes fuel for whatever comes next.
A strategy built for this goal looks very different from one built for total freedom. The mortgage isn’t the enemy here; it’s practically background noise.
3. Own the House: The Mortgage Is the Mission
For others, paying off the home is the defining milestone. It might be tied to a specific life event, retirement, a child leaving for college, or a decade anniversary of buying the place. The emotional significance of holding a clear title is real and worth taking seriously.
This version calls for a mortgage-first or mortgage-focused strategy. Extra principal payments, biweekly payment schedules, and careful amortization tracking all become central tools.
One thing worth understanding clearly: refinancing can look like progress toward this goal while quietly moving against it. Lowering a monthly payment by extending the loan term resets the amortization clock. Lifetime interest can actually increase even as the monthly number drops. That’s not automatically a bad move, but it’s a trade-off that’s easy to miss if the only number you’re watching is the monthly payment.
4. Cash Flow First: More Room in the Budget Every Month
Some households aren’t primarily focused on when debt ends. They’re focused on having more breathing room right now. Maybe income is variable. Maybe a child is starting school. Maybe the emergency fund feels dangerously thin.
For this version, the goal is reducing monthly obligations as quickly as possible. That might mean paying off a small car loan before a larger student loan, even if the interest-rate logic points the other way. The freed-up monthly cash matters more than the mathematical optimum.
This is also the version where refinancing to a lower payment can genuinely make sense, if the priority is monthly relief and the long-term interest cost is an acceptable trade-off. The key is making that trade consciously, not by accident.
5. Lower Risk: Protecting Against the Unexpected
Some people aren’t trying to be debt-free in any dramatic sense. They want a buffer. They want to know that if income dropped, or a major expense arrived unexpectedly, they wouldn’t immediately be in crisis.
For this version, debt reduction is less about the total balance and more about the ratio, debt relative to income, or total obligations relative to assets. Paying down the principal on a mortgage builds equity, which can provide real options in an emergency. Eliminating a car payment removes a fixed obligation that could otherwise become unmanageable.
A risk-reduction strategy might look quiet from the outside. It might not involve aggressive payoff timelines at all. But it’s a real and genuinely valuable goal.
6. Retiring Clean: Entering Retirement with No Payments
This version comes with a specific deadline: the day regular work income stops. The goal is to arrive at that date with no debt obligations, or at least no obligations that require employment income to cover.
For many households, this is actually the most urgent form of debt-free, even when retirement is still years away. The math is straightforward: debt that seems manageable on a working income can become genuinely difficult on a fixed income.
Planning for this version requires mapping payoff timelines against a target retirement date, and honestly assessing whether the current plan gets there in time. Tools that show the exact month a debt will be resolved can make that reckoning concrete rather than something vague you’ll figure out later.
Naming Your Goal Changes Everything
A payoff plan built for cash-flow relief looks nothing like one built for total freedom. A strategy optimized for retiring clean might deliberately set consumer debt aside for years. A household focused on owning their home outright needs to think about refinancing very differently than one focused on monthly breathing room.
None of these goals is the right one. They reflect different values, different household circumstances, and different ideas about what financial security actually feels like.
The most useful question to sit with isn’t “how do I pay off debt faster?” It’s a quieter one: What would I actually feel if this specific debt were gone?
That answer, your answer, is where the real strategy begins.
Take care of all 6 debt types: HERE
Your Debt Resolved publishes this article for general education only. It is not financial, legal, tax, or investment advice, and it is not a recommendation of any specific product, lender, or strategy. Mortgage acceleration involves voluntary extra principal payments. There is no guaranteed payoff date or savings amount. Your situation is unique; consult a licensed professional before acting. Individual results vary.